Français (France)
 Deutsch (DACH)
 Italiano (Italia)
 Dutch (Nederlands)
 English (United States)
 English (Canada)
 French (Canada)
IN THIS PAPER
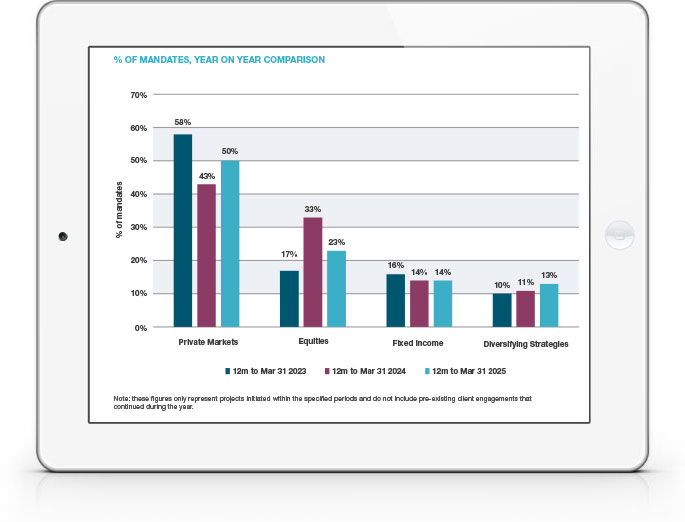
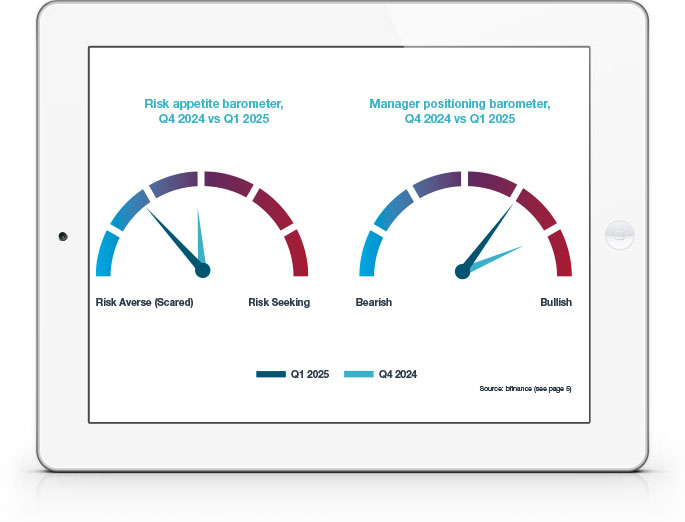
Equity searches, as a percentage of activity, declined year-on-year, albeit from a record-high 33% achieved in the prior 12-month period. However, demand for global equity strategies rebounded to 56%, reflecting renewed interest in diversification amid macro volatility. Emerging markets gained traction, with specific focus on India, Saudi Arabia, and GEM ex-China. Meanwhile, manager positioning has shifted defensively, with notable increases in cash, gold, and dividend-paying sectors as investors seek protection against stagflationary pressures..
Investment Grade Credit remained a focal point for asset owners, representing 33% of new searches in Q1, supported by stable yields and relatively attractive spreads. Multi-sector strategies continued to gain ground, accounting for 20% of fixed income mandates, while high yield interest declined to 7% as risk appetite moderated. Infrastructure debt and real estate debt were also notable beneficiaries, drawing capital from investors seeking structural income and downside protection.
Diversifying strategies captured 13% of new mandates, with hedge funds and alternative income vehicles seeing strong inflows. Alternative Risk Premia led performance, returning 3.7% in Q1, extending its run of quarterly gains as value, momentum, and quality factors outperformed. Directional strategies dominated new hedge fund searches, while market-neutral and absolute return approaches also saw increased demand amid rising dispersion and geopolitical uncertainty.
Private markets fundraising gained momentum in Q1, driven by private debt and infrastructure, both of which saw significant capital deployment through mega-fund closings. Real estate searches remained steady, with increasing interest in data centres, industrials, and European value-add strategies. However, private equity fundraising remains challenging, with secondaries and continuation vehicles attracting more investor interest than primary funds. Over the past three years, debt-focused strategies have captured a growing share of capital raised, reflecting investor demand for more income-oriented exposures.
WHY DOWNLOAD?
Each quarter, bfinance publishes information on investor activity, key market trends and manager performance. A quarterly snapshot of the key developments within equity, fixed income and alternative investments, including analysis of which asset manager groups performed well and which didn't.
Important Notices
This commentary is for institutional investors classified as Professional Clients as per FCA handbook rules COBS 3.5R. It does not constitute investment research, a financial promotion or a recommendation of any instrument, strategy or provider. The accuracy of information obtained from third parties has not been independently verified. Opinions not guarantees: the findings and opinions expressed herein are the intellectual property of bfinance and are subject to change; they are not intended to convey any guarantees as to the future performance of the investment products, asset classes, or capital markets discussed. The value of investments can go down as well as up.