Français (France)
 Deutsch (DACH)
 Italiano (Italia)
 Dutch (Nederlands)
 English (United States)
 English (Canada)
 French (Canada)
IN THIS PAPER
Allocators sought to better protect portfolios from an increasingly uncertain geopolitical and policy backdrop by prioritising income stability, inflation protection and diversification. The demand for these attributes was evident across both private and liquid market search activity, while appetite among our client base for risk assets remained resilient.
We certainly saw growing client interest in uncorrelated sources of alpha as our diversifying strategies business saw a sizeable increase in the share of search activity for market-independent hedge funds, relative to other hedge fund searches. Search activity overall for hedge funds was very high in 2025.
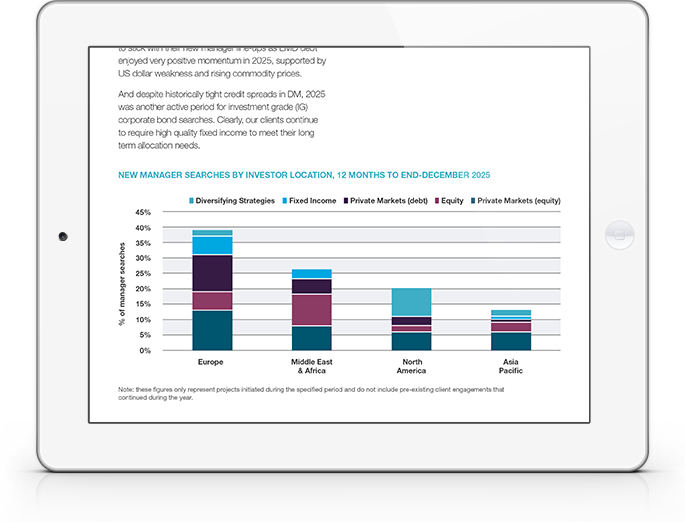
While several major equity indices ended the year near record or multi-year highs there was a decisive broadening in regional leadership away from the US and towards international and emerging market (EM) equities. Against this backdrop our EM-related searches struck almost 60% of total equity activity – a record high for bfinance.
We did not see the same trend as in equities to deploy fresh capital to emerging market debt (EMD). This absence of activity should, however, be seen in the context of a very active 2024 – it seems our clients were happy to stick with their new manager line-ups, as absolute EMD returns were supported by US dollar weakness and rising commodity prices.
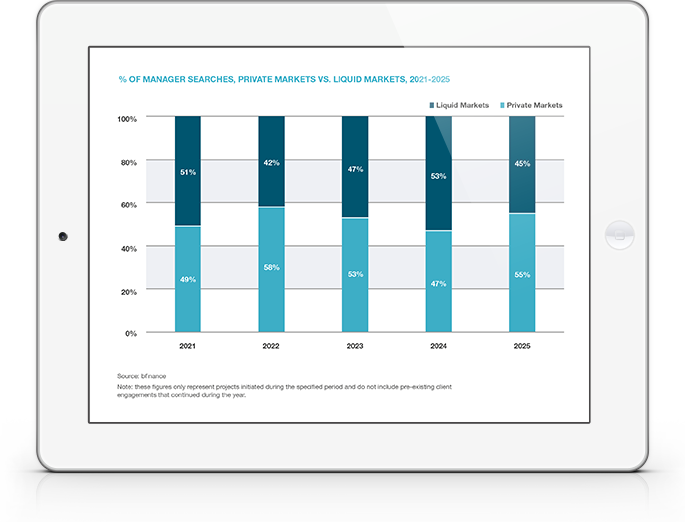
Within private debt, average credit spreads for direct lending remained attractive by longer-term historical standards, and fundraising remained strong. The segment represented more than 80% of total private debt fundraising over Q4, when overall flows picked up versus the prior quarter. Private debt searches represented 37% of all bfinance private markets searches, while private equity accounted for 19% of searches, where activity was focused on secondaries and lower-mid market buyout funds.
Real asset (real estate and natural capital and infrastructure) accounted for 44% of all private market searches (25% of all new bfinance manager searches in 2025). Interest in the energy and digital infrastructure “megatrends” continued to stimulate infrastructure interest. A sector perceived as both a yield substitute and inflation hedge, infrastructure recorded its highest-ever quarterly fundraising over Q4.
WHY DOWNLOAD?
Each quarter, bfinance publishes information on investor activity, key market trends and manager performance. A quarterly snapshot of the key developments within equity, fixed income and alternative investments, including analysis of which asset manager groups performed well and which didn't.
Important Notices
This commentary is for institutional investors classified as Professional Clients as per FCA handbook rules COBS 3.5R. It does not constitute investment research, a financial promotion or a recommendation of any instrument, strategy or provider. The accuracy of information obtained from third parties has not been independently verified. Opinions not guarantees: the findings and opinions expressed herein are the intellectual property of bfinance and are subject to change; they are not intended to convey any guarantees as to the future performance of the investment products, asset classes, or capital markets discussed. The value of investments can go down as well as up.