English (Global)
 Français (France)
 Deutsch (DACH)
 Dutch (Nederlands)
 English (United States)
 English (Canada)
 French (Canada)
IN THIS PAPER
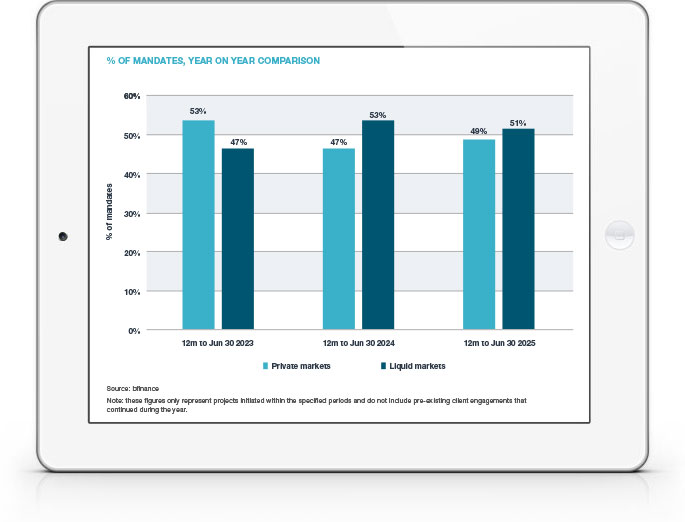
Equity search activity dipped slightly year-on-year to 27% of mandates, following a strong rebound in 2024. Global equity remained the dominant focus, while demand for emerging markets equity rose to 36% of equity searches—its highest level in recent years—with notable interest in India, Saudi Arabia and the GCC. Manager allocations reflect improved sentiment, though positioning remains measured.
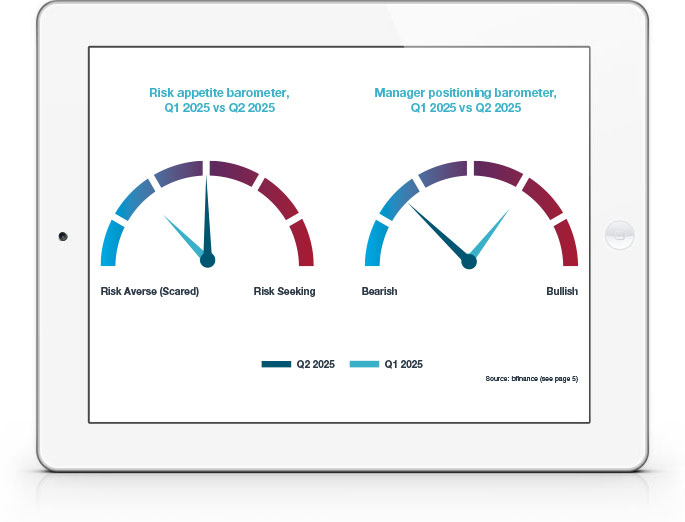
Fixed income activity remained steady at 13% of mandates, but with notable shifts beneath the surface. Investment grade credit searches rose to 46% of fixed income activity, as allocators sought resilient income and duration stability. Multi-sector strategies held firm, while demand for high yield and emerging market debt continued to recede. Manager sentiment reflected this cautious tone, with greater dispersion in spread compression and widening duration bets.
Diversifying strategies accounted for 11% of mandates, with hedge funds continuing to dominate the space. Equity long/short was the strongest-performing strategy cohort in Q2, with long-biased and market-neutral managers delivering strong alpha. Trend-following CTAs lagged, while multi-strategy and discretionary macro approaches showed renewed strength. ARP strategies posted muted results, reversing some of Q1’s strong gains.
Private markets fundraising remained subdued in Q2, with volumes around 25% below the five-year quarterly average. Yet signs of stabilisation emerged, led by a rebound in private equity buyout activity and renewed momentum in real estate. Large closes in tech-focused PE and opportunistic real estate funds signalled improved sentiment, while infrastructure and private debt saw softer fundraising despite ongoing mandate demand.
WHY DOWNLOAD?
Each quarter, bfinance publishes information on investor activity, key market trends and manager performance. A quarterly snapshot of the key developments within equity, fixed income and alternative investments, including analysis of which asset manager groups performed well and which didn't.
Important Notices
This commentary is for institutional investors classified as Professional Clients as per FCA handbook rules COBS 3.5R. It does not constitute investment research, a financial promotion or a recommendation of any instrument, strategy or provider. The accuracy of information obtained from third parties has not been independently verified. Opinions not guarantees: the findings and opinions expressed herein are the intellectual property of bfinance and are subject to change; they are not intended to convey any guarantees as to the future performance of the investment products, asset classes, or capital markets discussed. The value of investments can go down as well as up.