English (Global)
 Français (France)
 Deutsch (DACH)
 Italiano (Italia)
 English (United States)
 English (Canada)
 French (Canada)

IN THIS PAPER
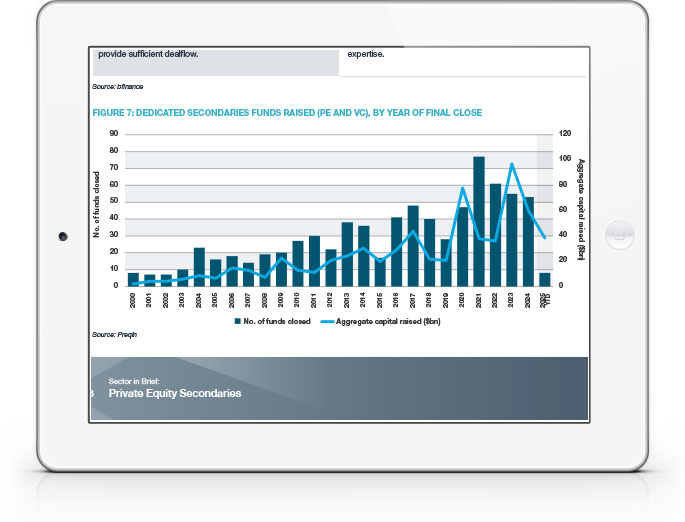
Secondary market trends in 2025: After a muted period, transaction volumes have increased, pricing has rebounded, and investor activity is diversifying across LP-led and GP-led deals. GP-led deals now account for nearly half the market, including a growing cohort of continuation vehicles.
The new buyer landscape: From mega dedicated funds to semi-liquid vehicles, the pool of secondaries investors is deepening. Semi-liquid funds—popular with wealth clients—now hold around 35% exposure to secondaries on average, raising new questions around liquidity management.
Strategy structures and access routes: The paper explores the various vehicles offering secondaries exposure—including generalist and niche dedicated strategies, fund-of-funds (FoFs), and semi-liquid portfolios—highlighting where innovation is reshaping access and risk profiles.
WHY DOWNLOAD?
Private equity secondaries have evolved into a vital liquidity mechanism and portfolio management tool, with growing relevance across institutional and private wealth channels. As market activity rebounds—driven by rising NAVs, stabilising interest rates and continued demand for liquidity—investors face a far more complex and nuanced environment than in previous cycles.
This report cuts through that complexity. We explore the changing structure of the secondaries market, from the resurgence of LP-led sales to the expanding universe of GP-led deals and continuation vehicles. We also assess the growing diversity of strategy types—from mega-funds to niche specialists and semi-liquid vehicles—and examine what investors should prioritise when selecting managers.
For investors considering a new allocation, reviewing existing exposures or assessing the broader implications of secondaries trends for their private markets programme, this briefing delivers timely, practical insight. The paper also supports investor due diligence with a clear set of criteria for assessing manager quality in a space where dispersion in performance remains significant.
Important Notices
This commentary is for institutional investors classified as Professional Clients as per FCA handbook rules COBS 3.5R. It does not constitute investment research, a financial promotion or a recommendation of any instrument, strategy or provider. The accuracy of information obtained from third parties has not been independently verified. Opinions not guarantees: the findings and opinions expressed herein are the intellectual property of bfinance and are subject to change; they are not intended to convey any guarantees as to the future performance of the investment products, asset classes, or capital markets discussed. The value of investments can go down as well as up.