English (Global)
 Français (France)
 Deutsch (DACH)
 Italiano (Italia)
 English (United States)
 English (Canada)
 French (Canada)
IN THIS PAPER
Allocators are increasingly recognising that broad market exposure alone may be less reliable than in the past. The opportunity set increasingly favours investors which are able to identify structural trends.
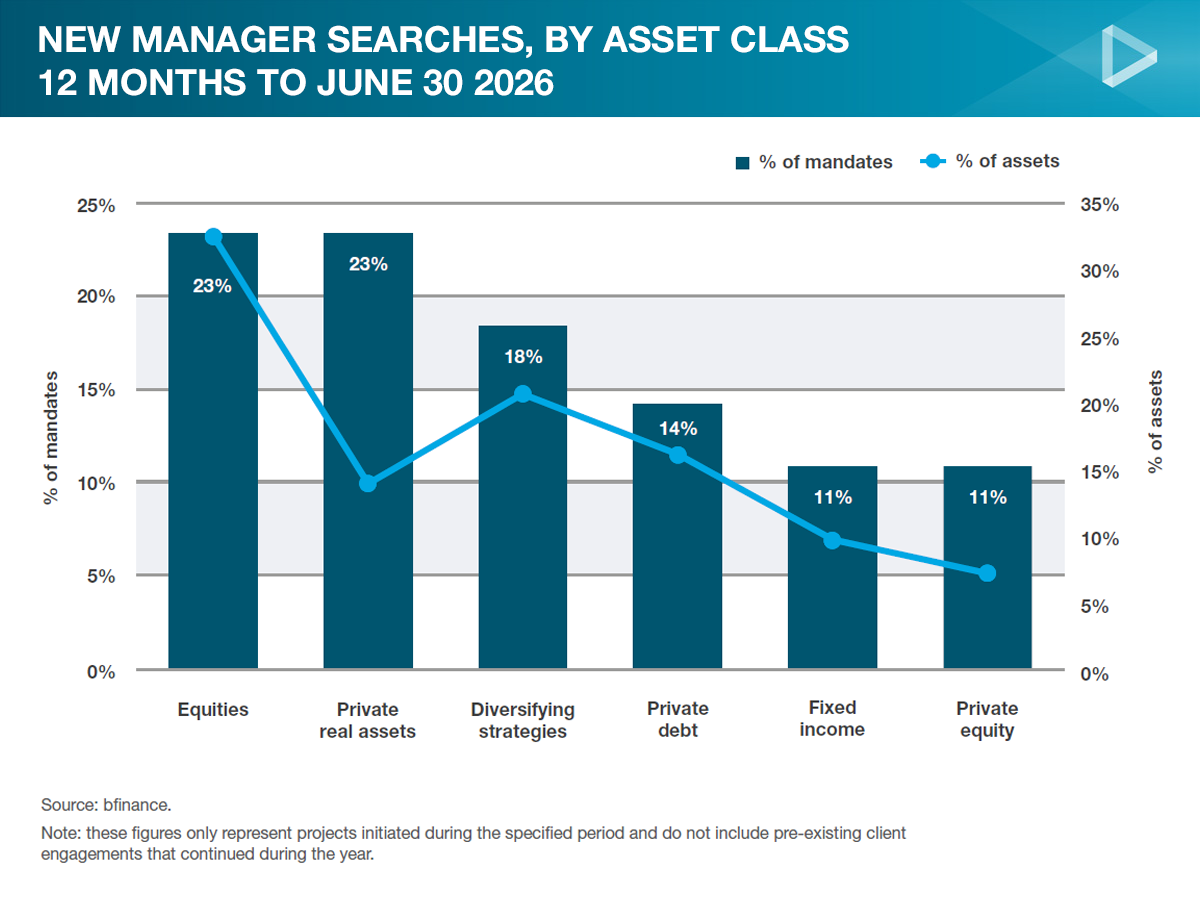
This has been reflected in strong investor interest in diversifying strategies, which enjoyed a particularly strong Q2, continuing a busy start to 2026.
Consistency of hedge fund returns has made the space hard to ignore. Meanwhile, overlay solutions were another area of strong demand for our diversifying strategies business, with projects spanning currency risk management and equity protection.
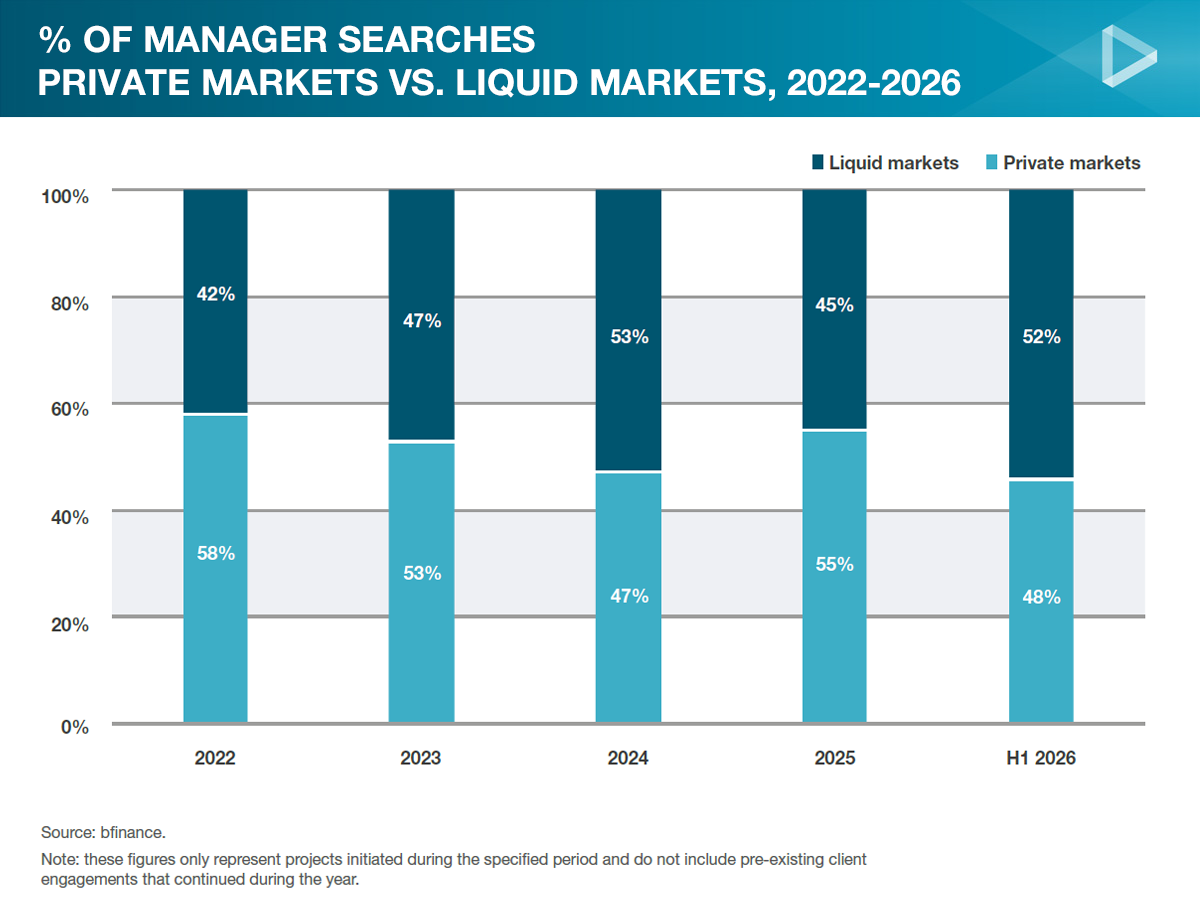
There was a shift in mix of private markets activity during Q2, as private debt and private equity search activity picked up. The renewed momentum in private debt was in line with a rebound in Q2 private debt industry fundraising.
Secondaries activity was an important driver of both the private debt and private equity activity. Opportunities have emerged for investors able to deploy capital when others are constrained or reluctant – the liquidity needs of existing investors have built as distributions have slowed amid ongoing weakness in PE exits.
Infrastructure activity continued to trend higher, from 18% of private markets mandates in the 12 months to June 2025 to 25% in the year to end-June 2026.
WHY DOWNLOAD?
Each quarter, bfinance publishes information on investor activity, key market trends and manager performance. A quarterly snapshot of the key developments within equity, fixed income and alternative investments, including analysis of which asset manager groups performed well and which didn't.
The period did little to detract from the challenges facing allocators relating to the growing dispersion within markets. Inflation outcomes, economic growth trajectories and policy responses are becoming increasingly differentiated across regions and sectors, and investors are having to adapt to a more fragmented, multipolar and less predictable world, where resilience and vulnerability coexist.
Important Notices
This commentary is for institutional investors classified as Professional Clients as per FCA handbook rules COBS 3.5R. It does not constitute investment research, a financial promotion or a recommendation of any instrument, strategy or provider. The accuracy of information obtained from third parties has not been independently verified. Opinions not guarantees: the findings and opinions expressed herein are the intellectual property of bfinance and are subject to change; they are not intended to convey any guarantees as to the future performance of the investment products, asset classes, or capital markets discussed. The value of investments can go down as well as up.