English (Global)
 Français (France)
 Deutsch (DACH)
 Italiano (Italia)
 English (United States)
 English (Canada)
 French (Canada)
IN THIS PAPER
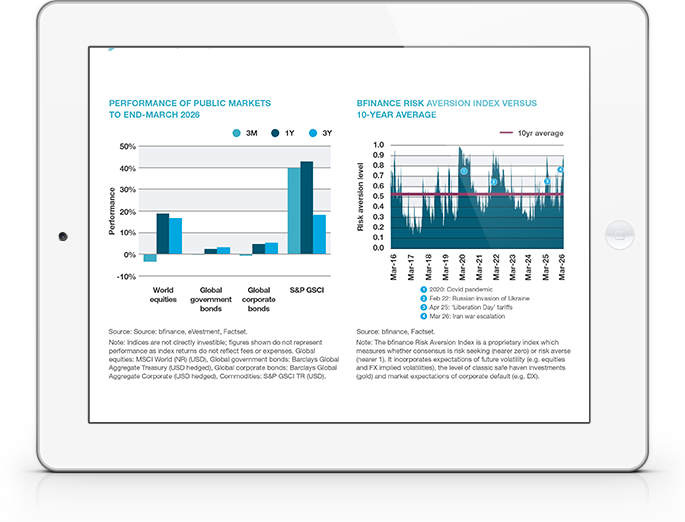
The Iran war threw up important short-to-medium term questions for allocators, chief among them the potential for a worsening growth/inflation trade-off of the kind experienced following the 1970s energy shocks — when economic output fell while inflation rose in a severe case of stagflation.
In terms of longer-term questions, the focus was on what a move to a multi-polar world order might mean for asset allocation. The quarter's events reinforced the need to rethink currency risk and pursue gradual portfolio diversification away from dollar assets — reflected in continuing client interest in currency overlay strategies.
Those allocating to private credit were confronted by corporate bankruptcy headlines (mischaracterised as direct lending stories), broad-brush AI disruption narratives and redemption activity in semi-liquid funds. Periods like this can, however, support better pricing and, often, stronger lender protections and tighter documentation.
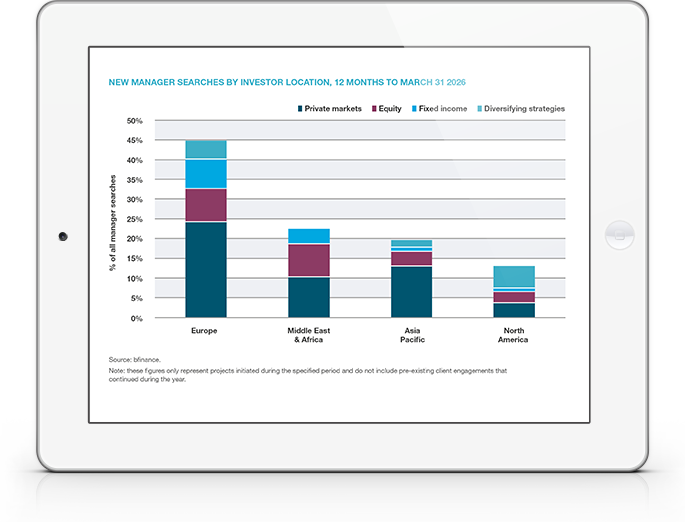
More broadly within private markets, bfinance saw pockets of strength amid the industry slowdown. Momentum in search activity for real assets — real estate, natural capital and infrastructure — remained strong, with infrastructure the standout, lifting real assets to account for more than half of total private markets activity in the year to end March 2026.
Private markets maintained a majority share of bfinance activity at 54% of mandates, compared to 46% for liquid markets. That said, listed equities dominated by volumes, accounting for close to 40% of search activity by assets over the trailing 12-month period, driven by a small number of outsized mandates.
Within fixed income, investment grade search activity remained steady. Despite corporate spreads trading at historically tight levels, demand has persisted from institutions requiring allocations to high-quality bonds. Multi-sector fixed income strategies also featured prominently, particularly among allocators seeking incremental yield with greater flexibility.
WHY DOWNLOAD?
Each quarter, bfinance publishes information on investor activity, key market trends and manager performance. A quarterly snapshot of the key developments within equity, fixed income and alternative investments, including analysis of which asset manager groups performed well and which didn't.
Important Notices
This commentary is for institutional investors classified as Professional Clients as per FCA handbook rules COBS 3.5R. It does not constitute investment research, a financial promotion or a recommendation of any instrument, strategy or provider. The accuracy of information obtained from third parties has not been independently verified. Opinions not guarantees: the findings and opinions expressed herein are the intellectual property of bfinance and are subject to change; they are not intended to convey any guarantees as to the future performance of the investment products, asset classes, or capital markets discussed. The value of investments can go down as well as up.