English (Global)
 Français (France)
 Deutsch (DACH)
 Italiano (Italia)
 English (United States)
 English (Canada)
 French (Canada)

IN THIS PAPER
India equity manager landscape: More than half of available strategies have 10+ years of track record, and over a third now manage >US$1 billion. Managers typically favour ‘growth’ styles and discretionary approaches, with a high prevalence of concentrated, all-cap portfolios.
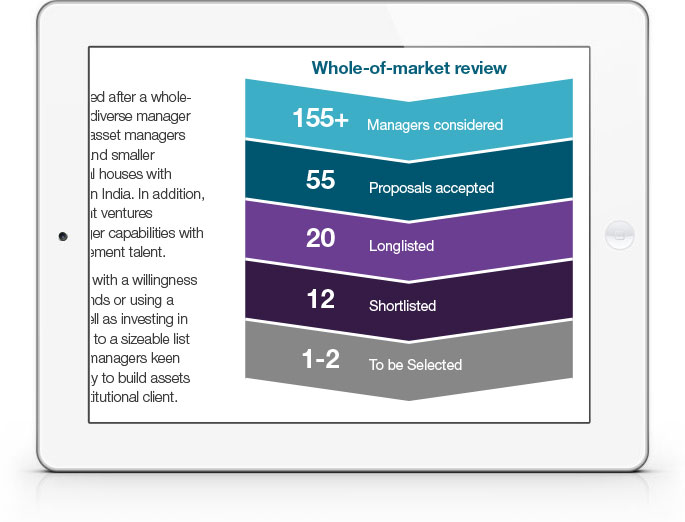
Inside a manager search: A recent search for a Middle Eastern institution illustrates key implementation challenges—including vehicle structure flexibility, the diversity of proposals (including from emerging boutiques), and investor-specific criteria for alpha generation and risk management.
Five key due diligence themes: Findings from this search highlight areas of focus such as tax-related NAV adjustments, ‘star PM’ risk, tariff exposure, and the difficulties of assessing outperformance across inconsistent datasets.
WHY DOWNLOAD?
India continues to capture investor attention as one of the most dynamic growth markets globally, with strong macroeconomic fundamentals and rising foreign inflows. Despite valuation concerns and pockets of geopolitical risk, sentiment has remained broadly constructive, underpinned by themes such as China-plus-one, reshoring, and the country’s large domestic consumption base.
Against this backdrop, institutional investors are showing a renewed appetite for dedicated India equity mandates—moving beyond broader EM allocations to implement direct exposure. Encouragingly, active managers in this sector have, on average, delivered significant long-term outperformance versus the MSCI India Index, even net of representative fees.
This report draws on a recent real-life case study to explore the nuances of manager research in India, from NAV adjustments due to capital gains tax provisions through to the prevalence of joint ventures, team structure, and ‘star PM’ dynamics. For investors exploring or reviewing this allocation, these insights offer practical guidance for more effective implementation.
Important Notices
This commentary is for institutional investors classified as Professional Clients as per FCA handbook rules COBS 3.5R. It does not constitute investment research, a financial promotion or a recommendation of any instrument, strategy or provider. The accuracy of information obtained from third parties has not been independently verified. Opinions not guarantees: the findings and opinions expressed herein are the intellectual property of bfinance and are subject to change; they are not intended to convey any guarantees as to the future performance of the investment products, asset classes, or capital markets discussed. The value of investments can go down as well as up.