English (Global)
 Français (France)
 Deutsch (DACH)
 Italiano (Italia)
 Dutch (Nederlands)
 English (United States)
 English (Canada)
IN THIS PAPER
Democratisation vs. retailisation: These two trends are reshaping private markets access, but their implications are very different. Democratisation opens the door to institutional-calibre strategies through reduced minimums and streamlined operations. Retailisation brings new product formats aimed at broader distribution—often with trade-offs in performance, structure and fee alignment.
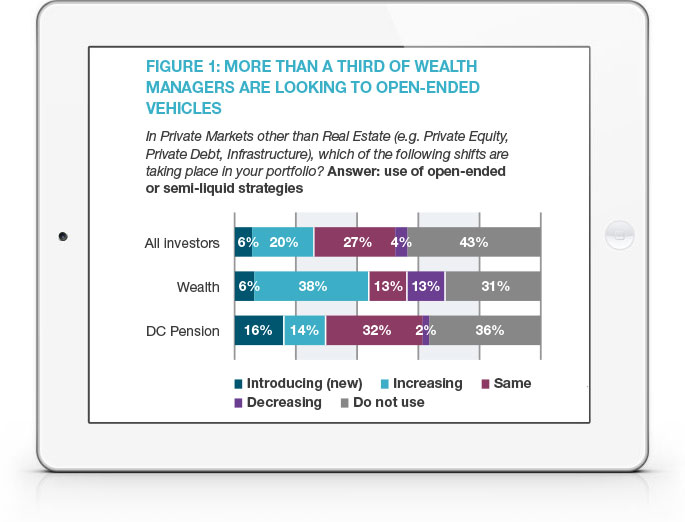
Evergreens and liquidity: Evergreen fund structures have now become flagship vehicles in the wealth space. This section highlights the evident growth in products (400+) in the sector, and considers both the benefits and risks: from investor-friendly simplicity to liquidity mismatches, performance opacity and cash drag.
How wealth managers are shaping the future: As adoption matures, leading firms are no longer just consumers of private markets, but rather they are becoming curators and constructors. The report profiles emerging models, from single-ticket products to advisor-enabling platforms for bespoke programme design.

WHY DOWNLOAD?
As client demand rises and platforms mature, private markets are no longer “alternative” for wealth managers, they are increasingly mainstream. Yet with expansion comes complexity. How can firms ensure access is translated into performance? Where does retail product innovation enhance outcomes, and where does it dilute them?
This paper provides a framework for understanding the evolving product landscape and the implications for both strategy design and portfolio implementation, and is the first in a series of spotlight articles which will go on to explore the evergreen universe through both an asset class lens and a liquidity lens.
For firms seeking to scale private markets effectively, the next critical challenge is no longer access, but rather it’s making the right calls: in product, in structure, and in strategy.
Important Notices
This commentary is for institutional investors classified as Professional Clients as per FCA handbook rules COBS 3.5R. It does not constitute investment research, a financial promotion or a recommendation of any instrument, strategy or provider. The accuracy of information obtained from third parties has not been independently verified. Opinions not guarantees: the findings and opinions expressed herein are the intellectual property of bfinance and are subject to change; they are not intended to convey any guarantees as to the future performance of the investment products, asset classes, or capital markets discussed. The value of investments can go down as well as up.