English (Global)
 Français (France)
 Deutsch (DACH)
 Italiano (Italia)
 Dutch (Nederlands)
 English (United States)
 English (Canada)
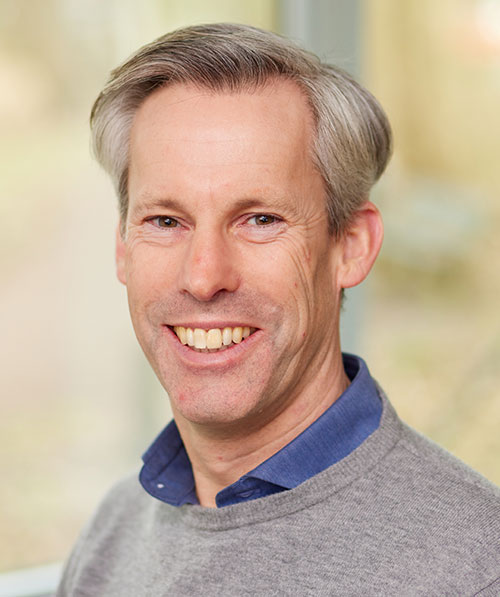 Roy Kroon
Senior Portfolio Manager, Private Credit Investments, PGB Pensioendiensten
While many asset owners continue to debate the role of impact investing, Pensioenfonds PGB has already made its choice. The Dutch pension fund has decided that new private markets investments should target measurable impact alongside financial returns, beginning with European impact direct lending. The decision reflects a growing conviction that pension funds can deliver both a strong retirement outcome and contribute to solving real-world challenges without sacrificing investment discipline.
PGB is one of the largest pension funds in the Netherlands, managing approximately €35 billion for around 450,000 participants from various sectors, including for instance the agricultural and food industry, the publishing industry and the graphics media and reprography industry. Roy Kroon, Senior Portfolio Manager, Private Credit Investments at the group’s in-house asset management company, sat down with bfinance Investor Spotlight to discuss the rationale for the move and the practical lessons learnt so far.
Why should pension funds look beyond ESG and towards impact?
For us, the question is simple: how do we deliver a good pension in a liveable world? ESG remains important but is not enough to achieve this. We see ESG primarily as a framework for managing risks and avoiding harm while impact investing goes further. We wanted to move beyond asking what we should avoid and start asking where our capital could make a tangible contribution while generating returns. If pension funds want to contribute meaningfully to challenges such as climate change, biodiversity loss or healthcare access, then capital needs to be directed towards solutions and real-world change rather than simply away from problems.
What led PGB to decide that all new private markets investments should be impact-focused?
There was no single moment when we made the decision that all new private market allocations should be impact for the foreseeable future. The decision evolved over recent years through discussions with stakeholders, the board and our members. Our members consistently told us that sustainability and real-world outcomes matter. At the same time, we were reviewing the portfolio from an ALM (asset liability management) perspective and exploring alternatives to allocations such as high yield credit and bank loans, where diversification benefits had become less compelling. These two developments came together naturally and led us to begin our journey with private credit (corporate direct lending). That is not to say the transition was without internal debate about a narrower universe, flexibility and opportunity cost. These concerns prompted robust discussion across the organisation. Ultimately, however, the board concluded that the potential benefits both in terms of real-world outcomes and long-term investment opportunities outweighed the constraints.
How did you define your impact themes?
We began by listening to our members. Regular member surveys on sustainability highlighted four systemic and partially interlinked themes that consistently emerged as priorities: climate transition, biodiversity, sustainable food systems and healthcare. By focussing on the themes which sit at the root of many of today’s sustainability challenges, PGB is able to identify the companies most likely to contribute to change. We are actively working on refining our theory of change and approach to allocating to these themes. Importantly however these themes are not rigid allocation targets. We still construct portfolios through a risk-return lens. The investment strategy comes first, but we expect capital to be deployed in ways that meaningfully contribute to those priority themes. Impact should strengthen investment outcomes, not replace investment discipline.
PGB structures decisions around four equal pillars: return, risk, costs and sustainability. In practice, does impact come with trade-offs?
So far, we have not seen evidence that it does. Private markets are naturally more expensive than public markets, but we have not observed a meaningful fee premium for impact versus non-impact private debt strategies. Likewise, our expectation is that impact direct lending should deliver risk-adjusted returns consistent with comparable non-impact strategies. We are not pursuing impact at the expense of financial outcomes. We expect investments to be investable, scalable and capable of generating market-level returns while also delivering measurable societal benefits.
How do you think about geographic exposure?
We do not have geographic limits in the investment plan, so technically the mandate is global. We started in Europe for private credit as the market is relatively well-developed and there are also attractive opportunities close to home. That said, we have avoided setting geographic impact targets. For example, investing locally can be appealing, but if domestic exposure becomes a rigid target, investors may end up compromising on risk or return. For us, local impact is a benefit when it emerges naturally, not a requirement.
Many investors still view emerging markets as too risky. Do you share that view?
Emerging markets (EM) require more homework, not necessarily less conviction. Perceived risks do not always reflect the reality. Governance, political and country risks need to be understood and can often be managed by investing alongside experienced partners, such as development finance institutions (DFIs) and NGOs. Equally, EM are incredibly diverse; each country in Asia, Latin America or Africa presents very different investment opportunities and risks so any allocation should be clearly defined. What makes them particularly interesting is the scale of potential impact because the impact achieved per dollar invested can be significantly higher than in developed markets (DM); the amount of impact per dollar can be up to four times as high in EM compared to DM. We see this as an area of opportunity rather than something to avoid.
What surprised you most when assessing the impact private credit universe?
Positively, the quality of responses to our request for information (RFI) questionnaires had improved compared with similar searches a couple of years ago. Some managers that were previously opportunistic did not engage this time, while others have invested heavily in building robust impact capabilities and strengthened their proposition. Less positively, not every manager claiming impact is delivering it. There remains a meaningful distinction between managers with dedicated impact strategies and those with strong track records essentially offering ‘enhanced ESG’ strategies. Conducting detailed due diligence, deeper than in a traditional search, and meeting managers in person is critical.
Impact measurement is often described as the weakest link. What does good reporting look like?
This is an area we are actively working on, and the industry sometimes overestimates the need for perfection on day one. We take a pragmatic approach. Managers should provide core impact information from the outset, including clear evidence on how investments align with our themes and objectives. Reporting can then mature over time. The good news is that data quality is improving rapidly. Managers are collecting more information, portfolio companies are becoming more responsive, and investor expectations are helping raise standards across the market. The key is not waiting for perfect reporting before allocating capital. Back managers with strong foundations and processes and work with them to strengthen reporting over time.
What advice would you give to other pension funds starting their impact journey?
Begin by defining your universe clearly. Impact markets are still evolving, so investors need clear criteria around strategy, scale, track record and manager characteristics. Otherwise, the opportunity set can quickly become overwhelming or indeed too narrow. A broad market mapping helped us understand the landscape before narrowing our focus. Be critical. Visit managers, challenge assumptions and test whether impact is genuinely embedded in investment decision-making or merely a label. Most importantly, don’t wait for a perfect market. Data will improve over time. What matters is building conviction, learning through experience and refining your approach. The opportunity set is expanding, manager quality is improving, and the market is becoming increasingly investable. For investors prepared to do the work, impact investing is no longer a niche concept; it is a practical and scalable way to align financial outcomes with real-world results.
Important Notices
This commentary is for institutional investors classified as Professional Clients as per FCA handbook rules COBS 3.5R. It does not constitute investment research, a financial promotion or a recommendation of any instrument, strategy or provider. The accuracy of information obtained from third parties has not been independently verified. Opinions not guarantees: the findings and opinions expressed herein are the intellectual property of bfinance and are subject to change; they are not intended to convey any guarantees as to the future performance of the investment products, asset classes, or capital markets discussed. The value of investments can go down as well as up.